VantageScore watches consumer credit resiliency surface again in August
Charts courtesy of VantageScore.
By subscribing, you agree to receive communications from Auto Remarketing and our partners in accordance with our Privacy Policy. We may share your information with select partners and sponsors who may contact you about their products and services. You may unsubscribe at any time.
The latest edition of CreditGauge from VantageScore highlighted more consistency and consumer resiliency unfolding in August in connection with credit scores and the automotive part of financial services.
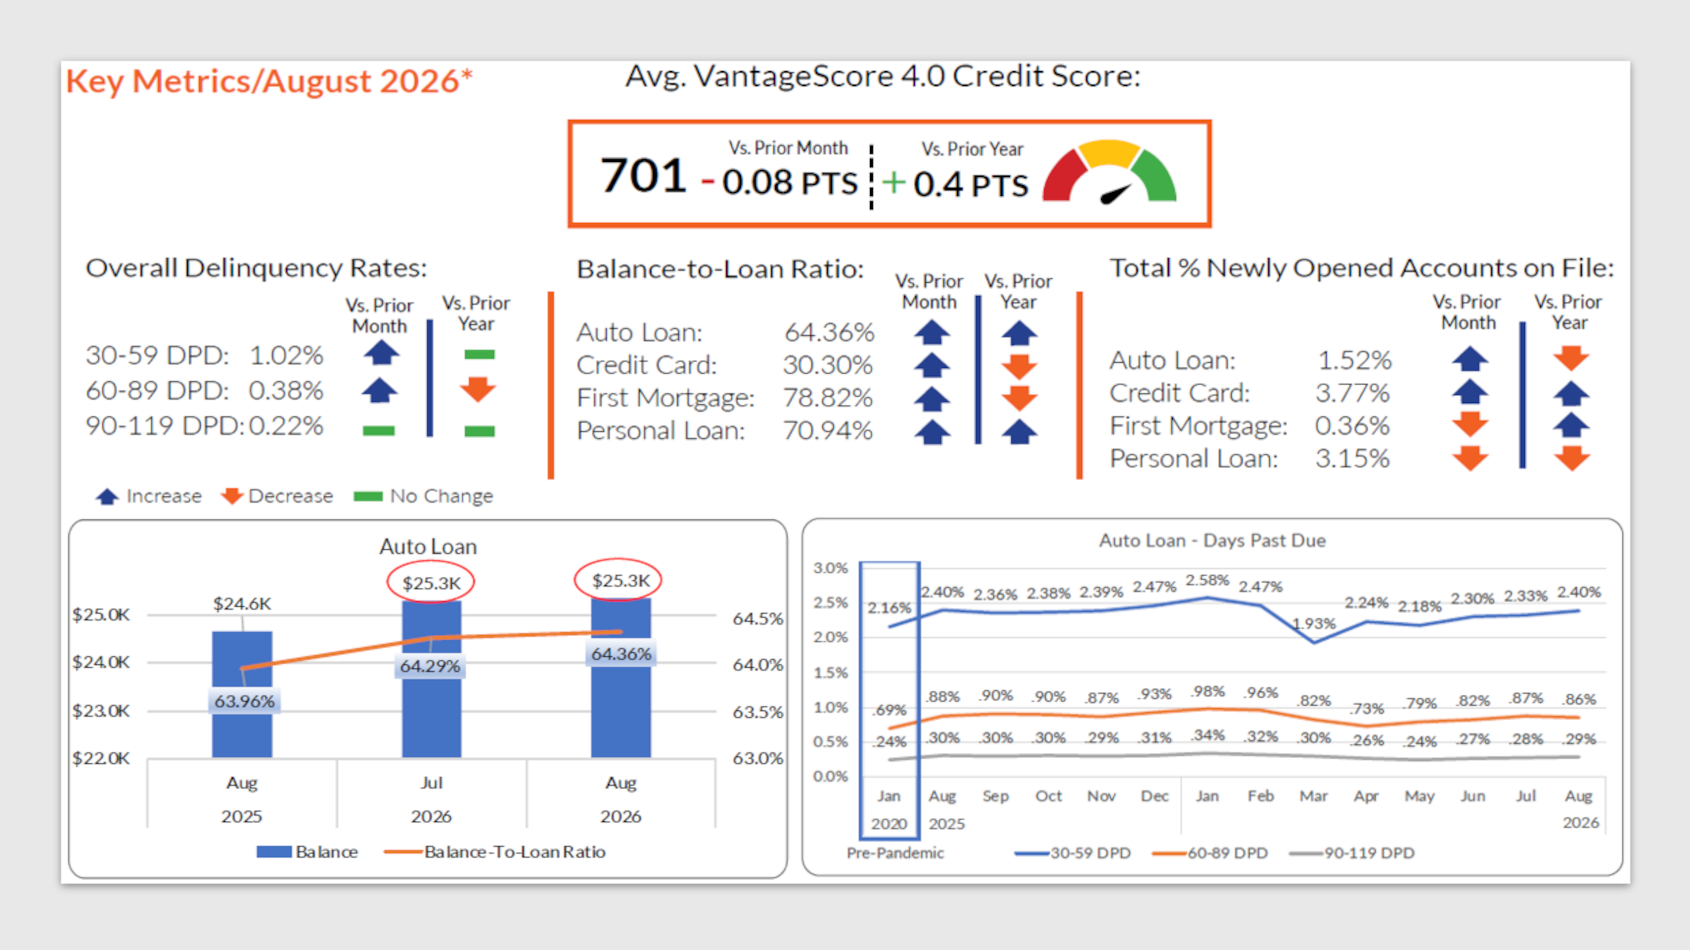
Analysts found that the average auto loan balance remained steady month-over-month, while increasing $706 or 2.9% compared to August of last year.
Noteworthy in auto finance, however, VantageScore reported the balance-to-loan ratio rose to 64.36% in August, the highest level in 13 months and 0.39% above a year ago.
“This rising ratio despite flat balances, suggests borrowers are paying down principal more slowly, likely reflecting affordability pressures from higher vehicle costs and rates,” VantageScore said in the report.
Looking at payments, analysts said “serious delinquencies remained contained year-over-year” since the rate of contracts 90 to 119 days past due came in at 0.29%.
For reference, VantageScore pointed out that the rate stood at 0.24% in January 2020.
Subscribe to Auto Remarketing to stay informed and stay ahead.
By subscribing, you agree to receive communications from Auto Remarketing and our partners in accordance with our Privacy Policy. We may share your information with select partners and sponsors who may contact you about their products and services. You may unsubscribe at any time.
Meanwhile, analysts noticed auto loan originations remained essentially flat from July to August across most generations, with millennials being the only cohort increasing by 0.1% to 1.6%.
Year-over-year, auto loan originations declined across most generations, with Gen Z posting the largest decline to 2.1% from 2.4%, according to VantageScore.
Taking a view of the overall credit landscape, analysts determined the average VantageScore 4.0 credit score remained essentially unchanged In August, “signaling continued stability in overall consumer credit quality.”
According to the report, the average VantageScore 4.0 credit score held at 701, declining by just 0.08 points from July.
“Average scores have remained within a narrow range over the past year, indicating that overall consumer credit quality remains stable despite continued affordability and borrowing-cost pressures,” analysts said.
The report went on to mention the distribution of consumers across VantageScore credit tiers held steady year-over-year.
VantageScore prime declined 0.2% from 32.6% to 32.4%, while VantageScore near-prime edged up 0.2% to 17.9%.
Subprime and super-prime both held flat at 18.8% and 30.9% respectively.
“The modest shift toward VantageScore near-prime, while consistent with underlying affordability pressure, remained marginal, reinforcing that overall consumer credit quality has been consistent despite payment stress in specific products and credit tiers,” analysts said.
And Atif Mirza, executive vice president and chief digital and insights officer at VantageScore, elaborated about why “consumer credit remains broadly resilient” in the video available in the window below.