Equifax webinar recaps how lenders are capturing growth amid affordability & other headwinds
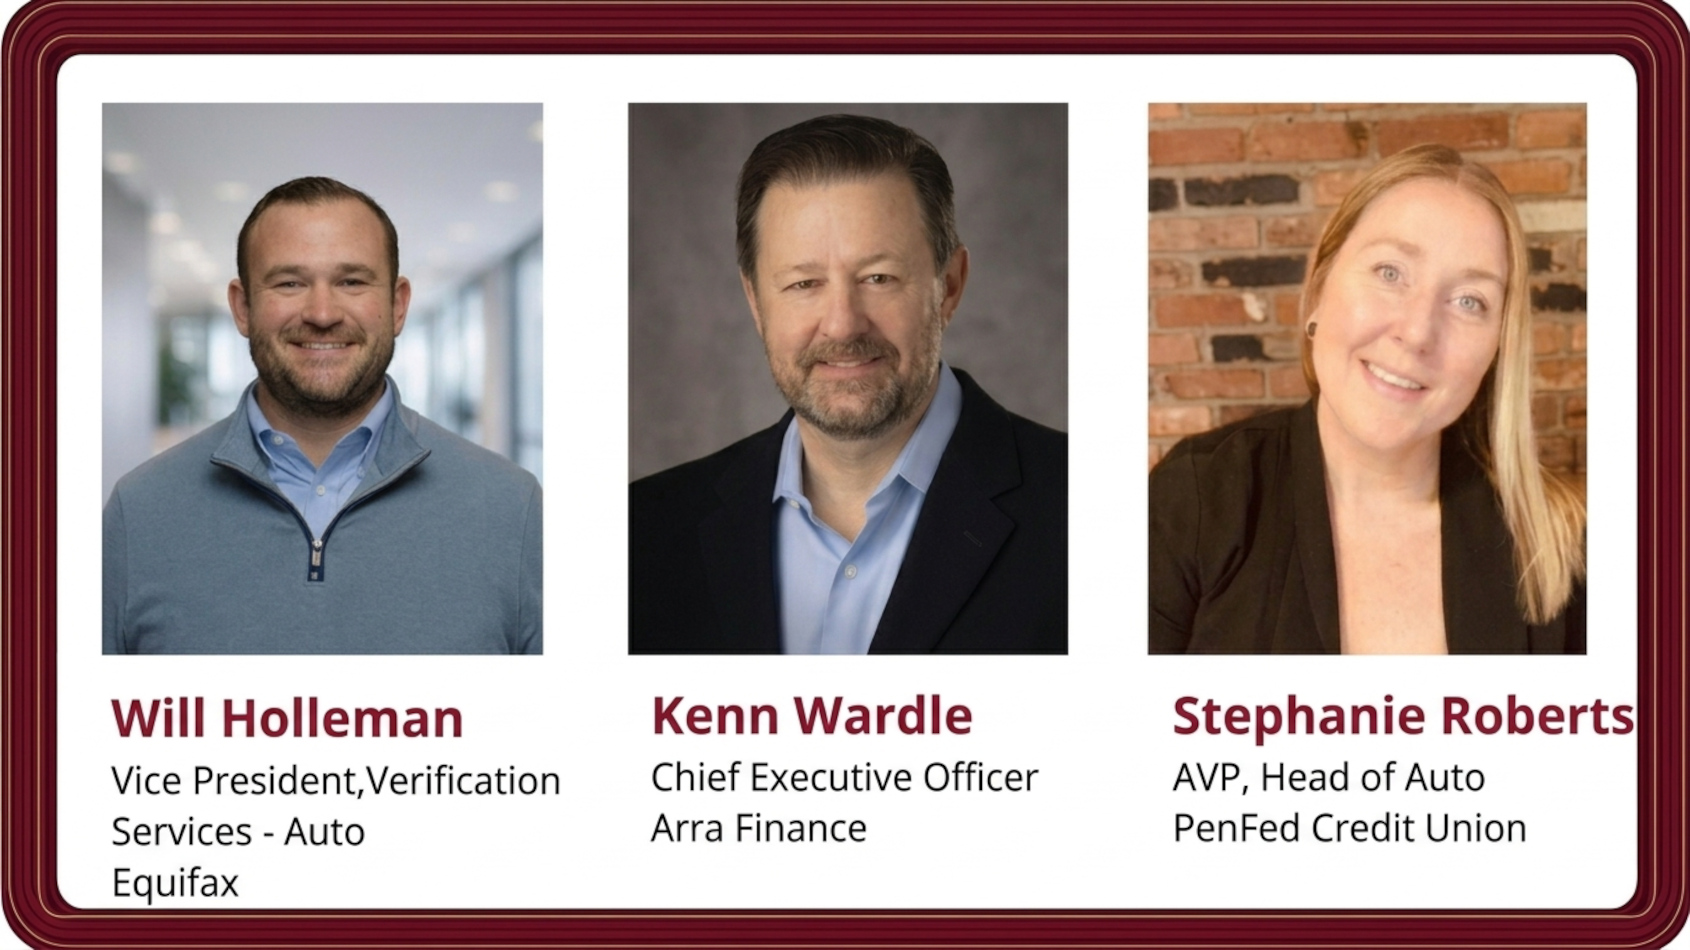
Screenshot courtesy of Equifax.
By subscribing, you agree to receive communications from Auto Remarketing and our partners in accordance with our Privacy Policy. We may share your information with select partners and sponsors who may contact you about their products and services. You may unsubscribe at any time.
Equifax recently hosted an informational webinar featuring Arra Finance chief executive officer Kenn Wardle and Stephanie Roberts, who is head of auto for PenFed Credit Union.
Among the topics Wardle and Roberts discussed:
—Stretching terms to fit monthly payments into consumers’ affordability limitations
—Using alternative data and artificial intelligence
—What conditions might be like in 2027 and beyond
“We are resilient. We adapt. And so, there are many ways that lenders are navigating some of the headwinds that we’ve seen persist over the last couple of years,” said Will Holleman, who is vice president of verification services – auto at Equifax and served as the webinar moderator for the session titled, High Vehicle Prices, Rising Risk: How Are Top Auto Lenders Capturing Growth Today?
Subscribe to Auto Remarketing to stay informed and stay ahead.
By subscribing, you agree to receive communications from Auto Remarketing and our partners in accordance with our Privacy Policy. We may share your information with select partners and sponsors who may contact you about their products and services. You may unsubscribe at any time.
“But we see elevated vehicle prices. New-car prices are over $50,000. But that isn’t just about the sticker,” continued Holleman, who also is among the speakers on the agenda for Used Car Week that starts on Monday in San Diego. “What we’re seeing is rising costs associated with that ownership, and that directly impacts the disposable income, household savings, especially across our subprime tiers. We’re also seeing negative equity trends. That’s been a big topic recently, as vehicle prices stay elevated, and Cox (Automotive) reports over 50% of auto loans are carrying negative equity into that next deal with underwater trade-in balances around that $6,000 to $7,000 range.
“So, we’re seeing lenders deal with that differently as some risk appetites have changed,” Holleman added.
One of the first paths lenders are taking to get deals completed is stretching contract terms.
“As we continue to see those amount of finances grow, we have to do what’s right for our consumers to manage those payments,” Roberts said. “A couple of things that we’ve seen is our average term increase, not significantly, but introducing medium terms is what I call them. Not 72, but like a 75-month term, so you’re not extending all the way to 84 months, just to get that payment more comfortable for a consumer.”
Wardle elaborated that lenders are often going beyond just terms, with finance companies seeking more details about the vehicle connected to the contract.
“It’s pretty similar tactics where extending loan terms where it makes sense on your better credit quality customers. I think there’s also opportunities for lenders in the space to make sure that they’re finding tools to offer,” Wardle said. “Maybe the structure doesn’t work on a particular asset, but you’d like to provide credit. So, finding opportunities to work with the dealer to identify other vehicles on their lot that the customer can better fit into within the right structure. It’s a little bit about term and also just about the structure of the vehicle, as well.”
Of course, discussing vehicles and financing brings loan-to-value ratios into the equation. That’s another component that’s becoming even more pronounced nowadays, according to Wardle.
“To say that LTV matters most when you have to pick a car up is because obviously there’s an impact to your recovery side,” Wardle said. “I think especially in my space where I’m in the more of the non-prime space, I think there’s a safe spot for LTV for the consumer to be successful in the loan. And in the instance of a deficiency, you’re not magnifying the deficiency by having it too high with LTV to start with.
“I’ve never been a fan of getting too far on the extremes of loan to value,” Wardle continued. “I think of it staying true to yourself from a credit perspective as to what got you here and then making tweaks from time to time. But I definitely would never focus too hard on letting the LTV creep up significantly.”
Later in the webinar, Holleman asked about types of alternative data outside of income and employment finance companies are examining nowadays.
“A couple of things that are top of mind is since we are direct to consumer, like that fraud aspect is even more highlighted, so alternative fraud data is very important for us because we don’t know if the person’s real or that there’s even a car at the end of the day because there’s not that dealer delivering the vehicle,” Roberts said. “For us, we’re pulling in a lot of fraud data sources to ensure that consumer and collateral are verifiable.
“Another thing that’s just top of mind as we talk to it that I don’t know that we’ve completely cracked the code for is as we think about affordability and things like that, is we have a lot of consumers engaging in buy now, pay later activity that isn’t completely like transparent to the lender,” Roberts continued. “To be able to better understand what people are making monthly payments on is becoming more and more difficult.
“And in that space where affordability is top of mind, I think we’re taking deeper looks at things like disposable income and (debt to income) to ensure affordability is taken care of. As we’re kind of aware that there’s other payments that consumers are making that are off bureau at this stage,” she went on to say.
Holleman then asked Wardle if artificial intelligence is becoming more of a help or a threat to auto financing.
“Definitely fraudsters are going to use different types of technology to continue trying to perpetrate fraud, and just making sure that your set suite of tools can keep up with that pace of change is something definitely that’s a concern and should be a focus of the leadership team,” Wardle said. “Personally, I’ve never really been that much of a fan of pushing AI specifically into my decisioning process on the application side. Largely speaking, the reason why I think theat is because at some point when there’s an administration change, we’ll have a lot more of the CFPB ramped back up.
“Where I see AI being really additive to lenders more in the back office and on the servicing side,” he continued. “There’s a lot of great efficiencies that can be gained there. We have an analyst in my finance department that has really taken different tasks, month-end type of tasks, from several days down to hours. That particular person has become a significantly more efficient analyst for us. I think that those benefits that you’ll see across your workforce are definitely worth pursuing AI strategies internally.”
In winding down the webinar, Holleman asked about what kind of headwinds lenders might be seeing for the remainder of the year and into 2027.
“Continued affordability concerns and the continued pressure on interest rates,” Wardle said. “Then depending on how much longer the different geopolitical issues persist, that’s going to continue to make it more continued difficulty for consumers.
“The way I’ve been discussing with potential investors at recent conferences has been the consumer is clearly stressed, but at this point in time they’ve continued to be resilient,” he continued. “If you look at it from the ABS side, there’s a little bit more concern on delinquency, but that’s only using lenders that rely on the ABS market, so you’re not really seeing delinquency trends of banks and credit unions, largely credit unions, and so forth. There’s still a lot of concern out there, and it’ll be interesting to watch and react to it as 2027 materializes.”